
是不是发现:
以前熬夜没事,现在睡不好,第二天整个人都没精神?
原因很多,其中一种就是:细胞能量下降。
身体每个细胞,都像一座发电厂。
辅酶Q10,就是帮助细胞产生能量的重要物质。
年龄越大,体内CoQ10水平会逐渐下降。
除了均衡饮食,保持运动、睡眠充足、减少压力,也有助于维持身体活力。
有活力,生活才有质量。
你每天睡几个小时?


是不是发现:
以前熬夜没事,现在睡不好,第二天整个人都没精神?
原因很多,其中一种就是:细胞能量下降。
身体每个细胞,都像一座发电厂。
辅酶Q10,就是帮助细胞产生能量的重要物质。
年龄越大,体内CoQ10水平会逐渐下降。
除了均衡饮食,保持运动、睡眠充足、减少压力,也有助于维持身体活力。
有活力,生活才有质量。
你每天睡几个小时?
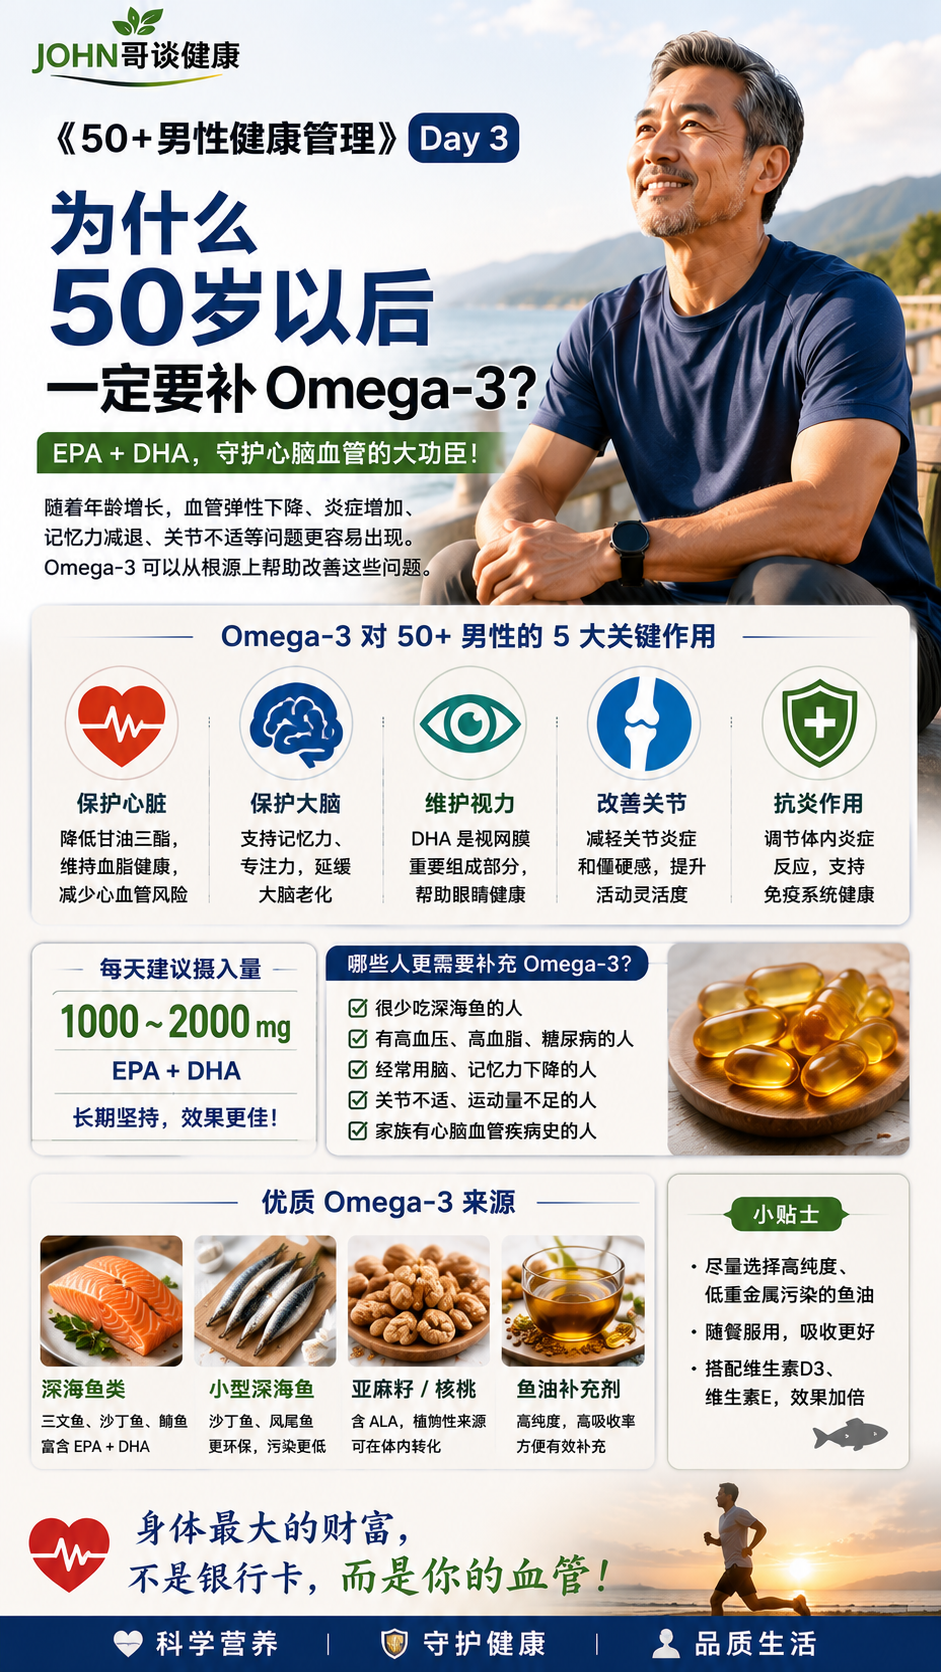
很多人天天补维生素,却忽略了真正保护心脑血管的重要营养: Omega-3。
EPA+DHA 有助于:
现代人吃鱼越来越少,Omega-3摄入普遍不足。
如果平时很少吃深海鱼,可以适当补充高品质鱼油。
身体最大的财富,不是银行卡,而是你的血管。
你一周吃几次鱼?
很多人50岁以后开始补钙。
其实,真正最先流失的,不是骨头,而是肌肉。
医学上叫做:肌少症。
肌肉减少以后:
所以50岁以后,每天最重要的营养就是:优质蛋白。
建议:
每天摄取约1.2~1.6克/公斤体重。
例如:
70公斤男性,一天最好达到84~112克蛋白质。
鸡蛋、鱼、鸡胸肉、牛肉、乳清蛋白,都是不错的选择。
肌肉,就是老年最好的养老金。
今天你一天能吃几个鸡蛋?

Surety Bond(保证保证书/履约保证) 是 RIBO Commercial Insurance 最容易混淆、但考试几乎每年都会考的内容之一。
很多考生把它当成一种保险,其实它和保险的原理有很大区别。
一句话理解:
Surety Bond 是一种”履约保证”,而不是传统意义上的保险。
例如:
建筑公司承包一个 $2,000,000 的学校工程。
学校担心:
“如果这家公司做到一半倒闭怎么办?”
于是学校要求:
请提供一份 Surety Bond。
这样,如果承包商无法完成工程,保证公司(Surety)会介入,确保工程完成或赔偿业主的损失(依保证条款而定)。
这是 RIBO 最爱考的知识点。
        Surety Company
        (保证公司)
             ▲
             │
             │ Guarantee
             │
Principal ─────────► Obligee
(承包商) (业主)就是:
负责完成合同的人。
例如:
他们承诺:
我会完成这份合同。
就是:
要求别人完成工作的人。
例如:
他们说:
“我要一份保证。”
例如保险公司或专业保证机构。
他们说:
“如果 Principal 不履约,我负责按照 Bond 条款处理。”
学校:
“我要盖体育馆。”
建筑商:
“我来盖。”
学校:
“请提供 Bond。”
保证公司:
“如果建筑商违约,我负责。”
于是:
School
   ▲
   │
Obligee

Builder
   │
Principal

Guarantee Company
   │
Surety保险:
例如火灾保险。
发生火灾:
保险公司赔偿后,通常不会向被保险人追回赔款(除非有欺诈等特殊情况)。
Surety Bond:
如果保证公司替承包商赔了钱,
可以向 Principal 追偿(Seek reimbursement)。
也就是说:
最终责任仍然是 Principal。
这是 Surety 和普通保险最大的区别。
| Insurance | Surety Bond |
|---|---|
| 转移风险 | 保证履约 |
| 两方关系 | 三方关系 |
| 赔款通常由保险公司承担 | Surety 可向 Principal 追偿 |
| 被保险人缴保费 | Principal 购买 Bond,但仍承担最终责任 |
作用:
保证中标后会签合同。
例如:
政府公开招标。
十家公司来投标。
其中一家报价最低。
后来他说:
“我不做了。”
Bid Bond 就会发挥作用。
考试关键词:Tender(招标)、Bid(投标)。
最重要。
保证:
工程会完成。
例如:
修桥
修学校
修医院
如果 Contractor 倒闭,
Surety 会负责按照 Bond 条款安排完成工程或赔偿。
保证:
工人和材料供应商能够收到款项。
例如:
避免因为承包商资金问题而拿不到钱。
保证:
工程完成后的保修期内,如果出现属于保修责任的问题,会负责处理。
例如:
桥梁交付后一年内出现因施工质量导致的裂缝。
Who promises to perform?
A Surety
B Obligee
C Principal
D Broker
答案:
✅ Principal
Who receives the promise?
A Principal
B Surety
C Obligee
D Contractor
答案:
✅ Obligee
Who guarantees performance?
A Principal
B Surety
C Owner
D Employee
答案:
✅ Surety
How many parties are involved?
A One
B Two
C Three
D Four
答案:
✅ Three
Surety pays a claim.
Who is ultimately responsible?
很多人会选:
Surety
实际上:
Principal
因为 Surety 一般有权向 Principal 追偿。
Principal = Performs(负责履约)

Obligee = Owns the project(接受承诺、要求履约)

Surety = Guarantees(提供保证)
再记一句:
3P 原则:Principal Performs,Promise goes to Obligee,Surety Guarantees.
按考试频率排序:
想象你要盖一栋办公楼:
只要记住这个场景,考试中关于 Surety Bond 的大部分选择题都能快速判断出来。
例如:
几乎都会要求:
因为金额巨大,公共资金需要更严格的保障。
这三个概念经常一起出现,也是 RIBO Commercial Insurance 中最容易混淆的一组。
这套题按照目前 RIBO Level 1 Commercial Lines 的考试蓝图设计,重点覆盖商业保险核心知识,包括商业财产、CGL、Business Interruption、Professional Liability、Crime、Marine、Surety、Cyber、Builders Risk、Boiler & Machinery 等内容,强调情景题与陷阱题。RIBO 的商业险部分重点在于识别风险、选择合适保障,以及理解保障范围与除外责任,而不是成为商业险专家。
1. A restaurant insures its building for $600,000. Replacement cost is $1,000,000, with an 80% coinsurance clause. A fire causes $200,000 damage.
How much will the insurer pay before deductible?
A. $150,000
B. $160,000
C. $200,000
D. $240,000
2. Which Commercial Property form provides the widest property coverage?
A. Named Perils
B. Basic
C. Broad
D. Comprehensive
3. Under Broad Form, theft of stock is generally covered only if:
A. Theft is specifically excluded
B. Building is insured
C. The building first suffers insured damage allowing entry
D. Employee commits theft
4. Which property would MOST likely require a Floater Policy?
A. Office desks
B. Inventory inside warehouse
C. Contractor’s tools moving between job sites
D. Building foundation
5. Builder’s Risk primarily covers:
A. Injuries to workers
B. Building under construction
C. Finished products after sale
D. Equipment breakdown
6. Which statement about Replacement Cost is TRUE?
A. Depreciation always applies.
B. Loss is settled based on market value.
C. Property usually must be repaired or replaced before full RC is payable.
D. RC automatically applies to every commercial policy.
7. Boiler & Machinery Insurance mainly covers:
A. Fire damage only
B. Mechanical/electrical breakdown
C. Flood
D. Employee theft
8. Which property is LEAST suitable for Replacement Cost?
A. New office furniture
B. Historic machinery no longer manufactured
C. New warehouse
D. Computers
9. Bailee insurance protects:
A. Property owner
B. Customers’ property in insured’s care
C. Employees
D. Building owner only
10. A dry cleaner damages customers’ clothing. Which policy responds?
A. CGL
B. Bailee Coverage
C. Crime Insurance
D. Builder’s Risk
11. Earnings Form primarily covers:
A. Net Profit only
B. Continuing Expenses only
C. Net Profit + Continuing Expenses
D. Gross Sales only
12. Profit Form primarily covers:
A. Gross Profit
B. Net Profit only
C. Payroll only
D. Inventory
13. Extra Expense Insurance is MOST useful for:
A. Manufacturer permanently closing
B. Hospital remaining operational after a fire
C. Vacant warehouse
D. Apartment building
14. Business Interruption coverage usually begins only after:
A. Power outage
B. Direct physical loss by an insured peril
C. Government order only
D. Employee resigns
15. Which business is MOST likely to purchase Extra Expense?
A. Jewelry store
B. Hospital
C. Self-storage
D. Vacant building
16. Which statement is FALSE?
A. Earnings Form includes continuing expenses.
B. Extra Expense minimizes interruption.
C. Business Interruption always covers loss from pandemics.
D. Physical damage usually triggers coverage.
17. Products Liability covers:
A. Damage during manufacturing only
B. Injury after product is sold
C. Employee injuries
D. Damage to insured’s own product
18. Completed Operations applies when:
A. Work is still in progress
B. Damage occurs after work is finished
C. Employee is injured
D. Vehicle collision occurs
19. Which is NOT covered by CGL?
A. Customer slips
B. Advertising injury
C. Employee workplace injury
D. Property damage to third party
20. Professional Liability is also called:
A. Crime Insurance
B. Errors & Omissions
C. Property Floater
D. Inland Marine
21. Cyber Liability MOST commonly covers:
A. Earthquake
B. Data breach
C. Boiler explosion
D. Product recall
22. Pollution Liability is needed because:
A. CGL always covers pollution.
B. Pollution is generally excluded under CGL.
C. Property insurance covers pollution.
D. Auto insurance covers pollution.
23. Umbrella Liability:
A. Replaces CGL
B. Provides broader and excess liability protection
C. Covers property damage only
D. Covers employee benefits
24. Which policy protects company directors from management decisions?
A. EPLI
B. D&O
C. Crime
D. Surety Bond
25. Employment Practices Liability mainly covers claims involving:
A. Fire damage
B. Wrongful dismissal and discrimination
C. Product defects
D. Theft
26. Which policy responds if an accountant gives negligent tax advice?
A. CGL
B. Property
C. E&O
D. Crime
27. Crime Insurance generally covers:
A. Employee dishonesty
B. Flood
C. Earthquake
D. Fire
28. Which Crime coverage protects against forged cheques?
A. Money & Securities
B. Forgery
C. Burglary
D. Fidelity Bond
29. Fidelity coverage mainly protects:
A. Customers
B. Employer from employee dishonesty
C. Directors
D. Buildings
30. Surety Bond differs from insurance because:
A. Three parties are involved.
B. Only two parties exist.
C. Losses are never recovered.
D. Claims are optional.
31. In a Surety Bond, who promises to perform?
A. Obligee
B. Surety
C. Principal
D. Insurer
32. Inland Marine typically covers:
A. Buildings
B. Mobile property
C. Employee injuries
D. Pollution
33. Ocean Marine covers:
A. Office equipment
B. Cargo transported internationally
C. Workers Compensation
D. Cyber attacks
34. Which policy is MOST appropriate for a software company storing customer information?
A. Builder’s Risk
B. Cyber Liability
C. Boiler Insurance
D. Ocean Marine
35. Product Recall Insurance mainly pays for:
A. Repairing buildings
B. Cost of recalling defective products
C. Employee wages
D. Equipment breakdown
36. Environmental Liability is especially important for:
A. Accounting firms
B. Restaurants only
C. Chemical manufacturers
D. Travel agencies
37. Which coverage protects against extortion involving ransomware?
A. Crime only
B. Cyber Liability
C. Property
D. Ocean Marine
38. A contractor accidentally damages a customer’s building while working. Which policy responds FIRST?
A. Builder’s Risk
B. CGL
C. Crime
D. D&O
39. A fire destroys inventory, and the business loses income while rebuilding. Which combination is MOST appropriate?
A. Property only
B. Business Interruption only
C. Property + Business Interruption
D. CGL only
40. Which commercial policy is MOST likely to be written on a Claims-Made basis?
A. Commercial Property
B. CGL
C. Professional Liability (E&O)
D. Builder’s Risk
| 章节 | 掌握程度 |
|---|---|
| Commercial Property | ★★★★☆ |
| Business Interruption | ★★★★★ |
| Coinsurance | ★★★★★ |
| Bailee/Floater | ★★★★★ |
| CGL | ★★★★☆ |
| Professional Liability | ★★★★★ |
| Crime | ★★★★★ |
| Cyber | ★★★★★ |
| Builders Risk | ★★★★☆ |
| Surety Bond | ★★☆☆☆ |
Named < Broad < Comprehensive
Earnings = Net Profit + Continuing Expenses
Profit Form = Gross Profit
Extra Expense = Keep Business Running
Slip & Fall → CGL
Bad Advice → E&O
Wrongful Dismissal → EPLI
Directors Sued → D&O
Data Breach → Cyber
Pollution → Environmental Liability
Moving Property → Floater
Customers’ Property → Bailee
Construction → Builder’s Risk
Equipment Breakdown → Boiler & Machinery
Employee Theft → Crime/Fidelity
Principal Performs
Surety Guarantees
Obligee Receives Promise
Professional Liability (E&O) = Claims-made
整体评价:
如果这是正式 RIBO Commercial 部分,你拿到 85% 已经相当不错。你现在最大的薄弱点只有两个:
把这两部分再巩固一下,你的 Commercial Insurance 模块基本就达到考试水平了。
50岁以后,真正开始拉开人与人的差距
很多人觉得:
50岁,只是年龄大一点。
其实不是。
50岁以后,身体进入了一个新的阶段。
很多慢性病,并不是50岁才开始,
而是年轻几十年的生活方式累积出来的结果。
健康不是等生病以后再重视,
而是在身体还没有报警之前,就开始保养。
记住一句话:
健康身体,是生活的底气。
以后每天,我都会分享一个50+男性最重要的健康知识。
一起健康老去。
留言告诉我:
今年你几岁了?

很多人年轻时拿健康换事业,
到了50岁以后,
却想拿财富换健康。
可惜的是,
有些东西,并不是花钱就能买回来。
50岁以后,身体会悄悄发生几个变化:
所以,这个年龄真正需要补的,
不是保健品,而是身体真正缺乏的营养。
建议重点关注:
#优质蛋白——预防肌少症
#Omega-3——保护心脑血管
#维生素D3——增强免疫、保护骨骼
#镁——改善睡眠、放松神经
#辅酶Q10——提升细胞能量、保护心脏
健康不是一朝一夕,
疾病也不是一天形成。
每天多运动一点,
每天睡好一点,
每天补足一点营养,
十年后的身体,一定会感谢今天的自己。
健康身体,是生活的底气;
照顾好自己,才能陪伴家人更久。
—— JOHN哥谈健康

很好!Business Interruption(营业中断保险) 是 RIBO Commercial Insurance 前三大高频考点,几乎每次考试都会出现 2–5 题。
很多考生不是不会,而是容易混淆:
下面这套题完全按照 RIBO 真题风格设计。
Business Interruption insurance is MOST likely triggered by:
A. A decline in sales due to increased competition.
B. Direct physical loss caused by an insured peril.
C. A change in market conditions.
D. Poor management decisions.
A restaurant closes because of a fire covered by its property policy.
Business Interruption insurance primarily reimburses:
A. The cost to rebuild the restaurant.
B. Lost business income during restoration.
C. The value of destroyed equipment.
D. Employee medical expenses.
Which expense is MOST likely covered under Extra Expense coverage?
A. Lost profits.
B. Renting a temporary location to continue operations.
C. Rebuilding a damaged warehouse.
D. Replacing inventory destroyed by fire.
A business suffers a covered fire loss and rents temporary office space so it can continue serving customers.
Which coverage responds?
A. Crime Insurance
B. Extra Expense
C. Commercial Property
D. Equipment Breakdown
Which statement about Gross Earnings Form is TRUE?
A. It only covers extra expenses.
B. It primarily protects gross earnings lost during interruption.
C. It covers employee dishonesty.
D. It replaces Commercial Property insurance.
Which form is MOST focused on Net Profit plus Continuing Expenses?
A. Gross Earnings Form
B. Extra Expense
C. Profits Form
D. Crime Form
A clothing store closes for two weeks after a covered fire.
Customers permanently shop elsewhere during the closure.
Business Interruption insurance generally covers:
A. Loss of income during the restoration period.
B. Future loss of customers forever.
C. Market share indefinitely.
D. Reduced sales caused by new competitors.
Business Interruption coverage usually ends when:
A. The insured earns a profit again.
B. Repairs should reasonably have been completed.
C. The insured decides to reopen.
D. One year after the loss.
Which of the following is NOT usually covered by Business Interruption insurance?
A. Continuing payroll (if insured)
B. Lost income
C. Damage to the building itself
D. Loss during restoration
A power outage affects an entire city.
The insured building suffers no physical damage.
Business Interruption coverage will MOST likely:
A. Respond automatically.
B. Not respond.
C. Pay only lost profits.
D. Cover only employee wages.
Which policy is specifically designed to help a business continue operating after a covered loss?
A. Commercial Property
B. Extra Expense
C. Crime Insurance
D. Boiler & Machinery only
Business Interruption insurance requires:
A. Employee negligence.
B. Direct physical damage from a covered peril.
C. A lawsuit.
D. A decline in market demand.
A manufacturer spends extra money to speed up production after a fire so customer orders are not lost.
Which coverage MOST likely pays?
A. Extra Expense
B. Crime
C. Commercial Property
D. Equipment Breakdown
Which statement is TRUE?
A. Business Interruption pays for every reduction in revenue.
B. Business Interruption requires a covered cause of loss.
C. Business Interruption covers losses from poor economic conditions.
D. Business Interruption replaces liability insurance.
After a covered fire:
Business Interruption insurance MOST likely pays until:
A. Day 90
B. Day 150
C. One full year
D. Until the business becomes profitable again
1. B
2. B
3. B
4. B
5. B

6. A
7. A
8. B
9. B
10. B

11. B
12. B
13. A
14. B
15. A
提示:
这 15 题几乎不需要计算,重点考查你是否能区分:
如果这套能达到 13/15(87%)以上,说明你对 Business Interruption 已经达到 RIBO Level 1 的考试水平。
Coinsurance(共同保险) 是 RIBO Commercial Insurance 最爱考的计算题。正式考试通常有 1–3 题,而且很多人因为忘记公式或不会判断是否有处罚而失分。
Building Value × Coinsurance %
例如:
Building Value = $800,000
Coinsurance = 80%
Required Insurance =
$800,000 × 80% = $640,000
如果:
Actual Insurance ≥ Required Insurance
➡ 没有 Coinsurance Penalty
赔全部损失(最高不超过保额)。
如果:
Actual Insurance < Required Insurance
➡ 使用公式:赔偿=应投保额实际保额×损失金额
A warehouse is worth $600,000.
It has an 80% coinsurance clause.
The owner purchases $400,000 insurance.
A fire causes $120,000 damage.
How much will the insurer pay (before deductible)?
A. $80,000
B. $100,000
C. $120,000
D. $400,000
A building is worth $1,000,000.
Coinsurance = 90%
Insurance carried = $900,000
Loss = $300,000
How much is payable?
A. $270,000
B. $300,000
C. $900,000
D. $1,000,000
A building is worth $500,000.
Coinsurance = 80%
Insurance = $300,000
Loss = $100,000
Payment?
A. $60,000
B. $75,000
C. $80,000
D. $100,000
Property value = $900,000
Coinsurance = 80%
Insurance purchased = $720,000
Loss = $500,000
Payment?
A. $400,000
B. $450,000
C. $500,000
D. $720,000
Property value = $700,000
Coinsurance = 80%
Insurance = $350,000
Loss = $140,000
Payment?
A. $87,500
B. $100,000
C. $120,000
D. $140,000
Property value = $1,200,000
Coinsurance = 90%
Insurance = $900,000
Loss = $180,000
Payment?
A. $150,000
B. $160,000
C. $180,000
D. $900,000
Property value = $400,000
Coinsurance = 80%
Insurance = $320,000
Loss = $60,000
Payment?
A. $48,000
B. $60,000
C. $64,000
D. $320,000
Property value = $800,000
Coinsurance = 90%
Insurance = $600,000
Loss = $180,000
Payment?
A. $150,000
B. $160,000
C. $170,000
D. $180,000
Property value = $500,000
Coinsurance = 80%
Insurance = $500,000
Loss = $450,000
Payment?
A. $400,000
B. $450,000
C. $500,000
D. Depends on depreciation
A commercial building has:
How much should be paid (before deductible)?
A. $360,000
B. $400,000
C. $500,000
D. $600,000
1. B
2. B
3. B
4. C
5. A
6. A
7. B
8. A
9. B
10. B
建议不要用计算器。
RIBO 考试中的 Coinsurance 数字通常设计得可以心算,熟练后每题大约 30 秒就能完成。
我们已经把 Commercial Property、CGL、Business Interruption、Crime、Professional Liability、Commercial Auto、Builders Risk、Bailee、Floater、Cyber、Umbrella、D&O、EPLI、Environmental 等内容都学完了。
下面这套是RIBO Level 1 真题风格综合模拟(40题),难度比正式考试略高,以陷阱题为主。
规则:
A $160,000 loss occurs.
How much will the insurer pay (before deductible)?
A. $100,000
B. $125,000 50/80*80%*16
C. $160,000
D. $500,000
Replacement Cost coverage requires
A. the building be rebuilt at another location.
B. depreciation always applies.
C. the damaged property be repaired or replaced.
D. proof of market value.
Which property is MOST likely insured under an Installation Floater?
A. Office furniture
B. Plumbing materials awaiting installation
C. Employee tools
D. Finished inventory
Builder’s Risk insurance ends
A. whenever construction stops.
B. after occupancy or project completion, whichever occurs first.
C. one year after construction starts.
D. only after final payment.
Which statement about Vacancy is TRUE?
A. Vacancy never affects coverage.
B. A vacant building increases moral hazard only.
C. Vacancy may reduce or suspend certain coverages.
D. Vacancy only matters for residential risks.
Business Personal Property usually includes
A. land.
B. stock.
C. foundations.
D. underground pipes.
Equipment Breakdown insurance mainly covers
A. gradual wear and tear.
B. sudden accidental mechanical breakdown.
C. flood.
D. theft.
Which loss is MOST likely covered under a Commercial Property policy?
A. Earthquake (without endorsement)
B. Flood (without endorsement)
C. Fire
D. War
An insured intentionally exaggerates the amount of loss after a fire.
This is
A. concealment.
B. material change.
C. fraud.
D. salvage.
Which property is MOST appropriate for a Bailee’s Customers policy?
A. Restaurant furniture
B. Customer clothing at a dry cleaner
C. Company computer
D. Delivery truck
Business Interruption insurance generally requires
A. bodily injury.
B. direct physical damage by an insured peril.
C. negligence.
D. theft only.
Extra Expense insurance primarily pays for
A. rebuilding the building.
B. continuing normal operations.
C. replacing inventory.
D. employee lawsuits.
Which form mainly covers loss of NET PROFIT plus continuing expenses?
A. Extra Expense
B. Gross Earnings
C. Profits Form
D. Crime
A restaurant closes because customers are afraid after nearby crime, but the restaurant itself suffers no property damage.
Business Interruption responds?
A. Yes
B. No
C. Only if sales decrease 25%
D. Only under Crime insurance
Which expense usually continues during a shutdown?
A. Cost of raw materials
B. Utility costs tied completely to production
C. Property taxes
D. Shipping expenses
CGL covers
A. poor workmanship itself.
B. bodily injury to third parties.
C. employee injuries.
D. expected damage.
Products Liability applies after
A. products leave the insured’s possession.
B. products are manufactured.
C. products are advertised.
D. products are designed.
Completed Operations coverage applies
A. while work is underway.
B. after work has been completed.
C. before construction starts.
D. only to products.
Contractual Liability
A. is always excluded.
B. may be covered for insured contracts.
C. covers criminal fines.
D. replaces professional liability.
Which claim is MOST likely excluded under CGL?
A. Customer slips.
B. Advertising injury.
C. Intentional assault by insured.
D. Damage caused by falling sign.
Pollution coverage under CGL is
A. unlimited.
B. automatically included.
C. very limited.
D. identical to Environmental Liability.
A contractor accidentally damages a client’s building while working.
Most likely covered under
A. Builder’s Risk.
B. CGL.
C. Crime.
D. D&O.
Which claim belongs under Products Liability?
A. Employee injured by machine.
B. Customer injured by defective toaster.
C. Building burns during construction.
D. Contractor falls off ladder.
Which coverage protects against libel and slander?
A. Property insurance
B. Personal & Advertising Injury
C. Crime
D. Inland Marine
Which statement is TRUE?
A. CGL covers every lawsuit.
B. CGL pays criminal penalties.
C. Defence costs may be covered.
D. CGL covers breach of contract automatically.
Employee Dishonesty covers
A. employee injury.
B. theft by employees.
C. theft from employees.
D. customer fraud.
Forgery insurance covers
A. counterfeit merchandise.
B. forged cheques.
C. stolen inventory.
D. cybercrime.
E&O insurance protects
A. buildings.
B. professionals against negligence claims.
C. directors.
D. company vehicles.
D&O insurance mainly protects
A. shareholders.
B. directors and officers.
C. employees.
D. customers.
EPLI covers claims involving
A. pollution.
B. wrongful dismissal.
C. burglary.
D. product defects.
Cyber Liability MOST likely covers
A. hail damage.
B. data breach response costs.
C. machinery breakdown.
D. flood.
Environmental Liability primarily covers
A. employee theft.
B. pollution claims.
C. vehicle collision.
D. professional negligence.
Umbrella Liability generally
A. replaces all primary insurance.
B. provides additional liability limits.
C. covers property only.
D. eliminates deductibles.
Which policy is MOST appropriate for a courier transporting customers’ goods?
A. Homeowners
B. Bailee
C. Cargo/Transportation Floater
D. Builder’s Risk
A lawyer gives incorrect legal advice causing financial loss.
Which policy responds?
A. CGL
B. Crime
C. Professional Liability (E&O)
D. Property
A hacker encrypts company files and demands payment.
Which insurance is MOST relevant?
A. Builder’s Risk
B. Cyber Liability
C. Inland Marine
D. Equipment Breakdown
Crime insurance usually covers
A. wear and tear.
B. mysterious disappearance only.
C. theft of money by employees.
D. market loss.
Which policy protects customer property temporarily in the insured’s care?
A. Bailee
B. Umbrella
C. EPLI
D. D&O
A company pollutes groundwater over several years.
Most appropriate insurance?
A. CGL
B. Property
C. Environmental Liability
D. Crime
Which statement is MOST correct?
A. Umbrella always covers every excluded loss.
B. E&O and CGL provide identical protection.
C. Cyber insurance may pay notification costs after a breach.
D. Builder’s Risk covers employee theft.
1. A
2. C
3. B
4. B
5. D
6. B
7. B
8. C
9. C
10. B

11. B
12. B
13. A
14. B
15. B

16. B
17. A
18. B
19. A
20. C
21. D
22. A
23. B
24. B
25. C

26. B
27. A
28. B
29. B
30. B
31. B
32. B
33. B
34. C
35. C
36. B
37. C
38. A
39. C
40. C
做完后,我会像 RIBO 阅卷老师一样:
按照我们最近几周的学习情况来看,你在 Commercial Insurance 的基础已经比较扎实了。从最初学习 Commercial Property、CGL、Business Interruption、Crime、Cyber、Professional Liability 到现在,正确率已经稳定在 80% 左右。这说明知识框架已经建立起来了。
我预计,把这三个专项练完后,你的商业保险部分可以稳定达到 90%+。